

The DOI matches its Crossref record; 24 of the 24 references it cites were found in a registry or an index.
Entropy-Based Financial Asset Pricing
Open accessAbstract
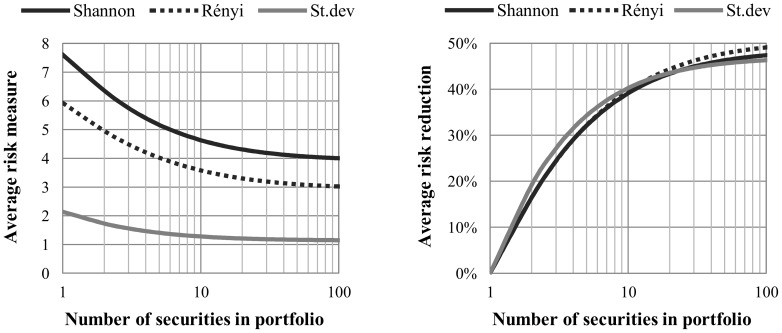
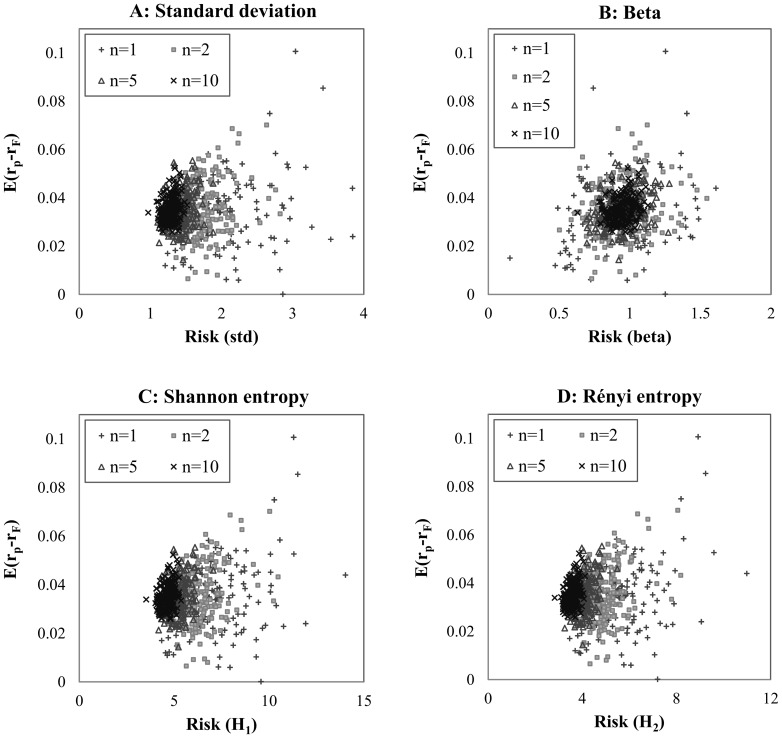
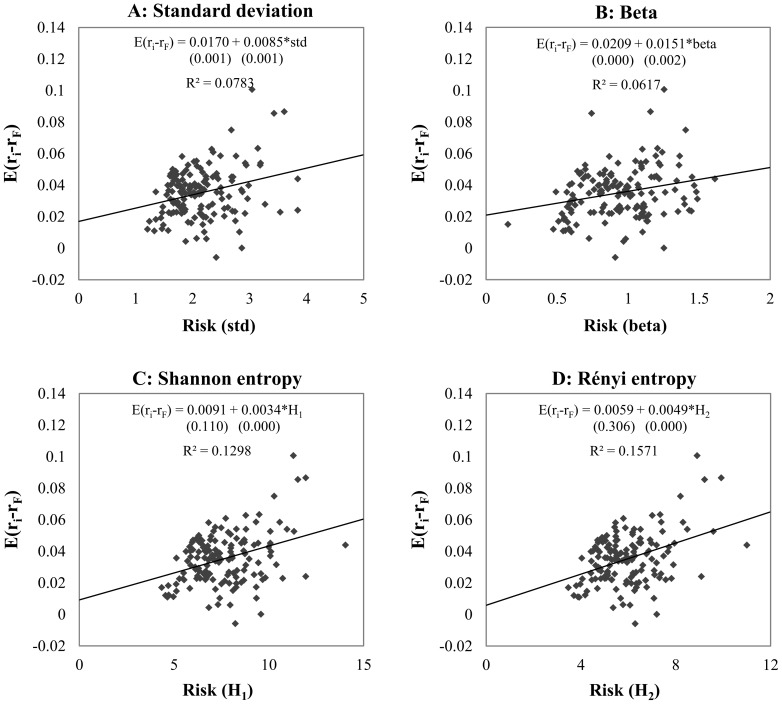
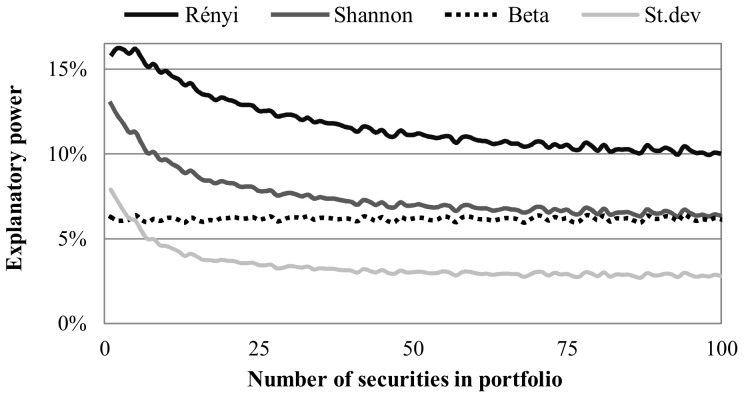
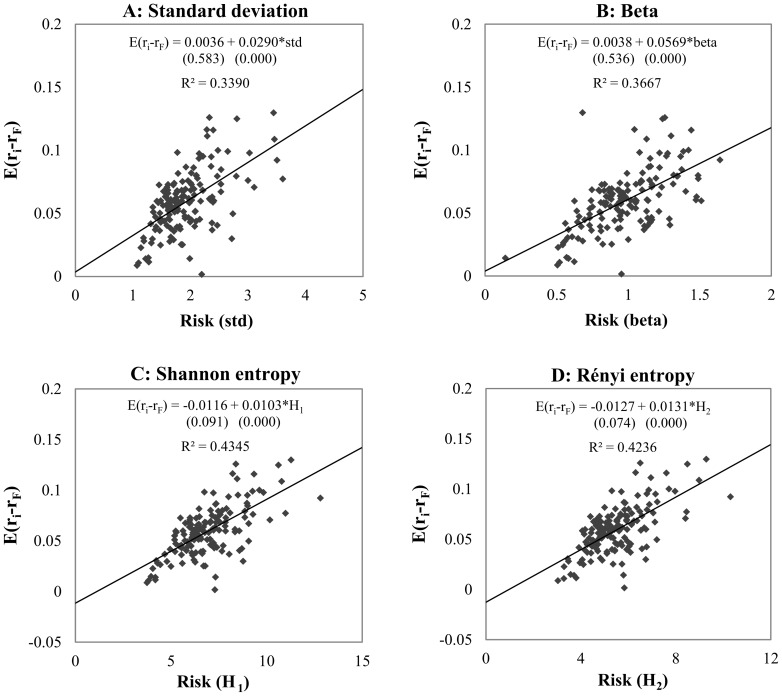
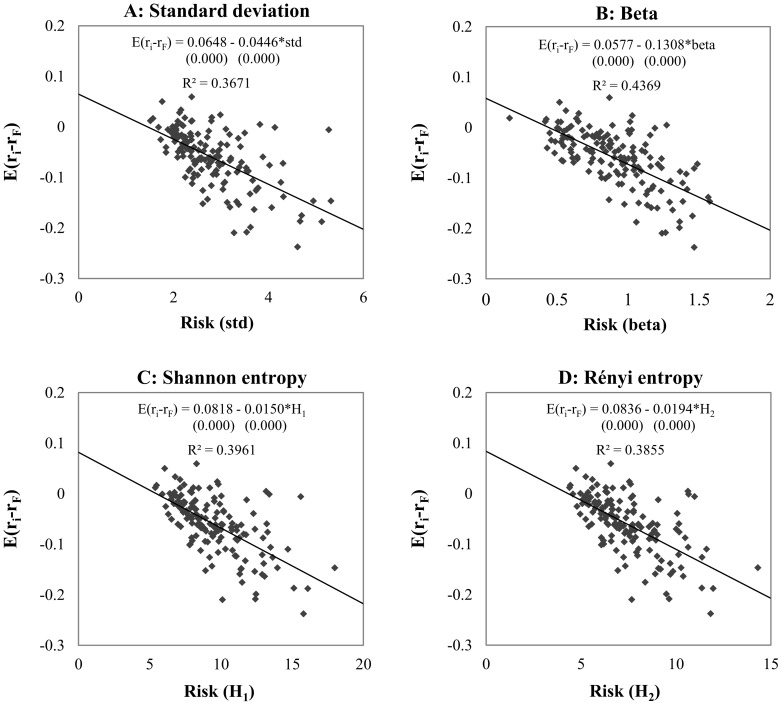
We investigate entropy as a financial risk measure. Entropy explains the equity premium of securities and portfolios in a simpler way and, at the same time, with higher explanatory power than the beta parameter of the capital asset pricing model. For asset pricing we define the continuous entropy as an alternative measure of risk. Our results show that entropy decreases in the function of the number of securities involved in a portfolio in a similar way to the standard deviation, and that efficient portfolios are situated on a hyperbola in the expected return-entropy system. For empirical investigation we use daily returns of 150 randomly selected securities for a period of 27 years. Our regression results show that entropy has a higher explanatory power for the expected return than the capital asset pricing model beta. Furthermore we show the time varying behavior of the beta along with entropy.
Overview
The claims and statistics of this paper haven’t been checked yet.
Run the check — free, no account needed. It reads the open-access text and checks the sources it cites.
Integrity signals
Registry
Cites
Statistics
Figures
Verification
Claims the paper makes
The claims and statistics of this paper haven’t been checked yet.
Run the check — free, no account needed. It reads the open-access text and checks the sources it cites.
Claims other papers make about this one
Each is checked against this paper’s own text: does it say what the citing paper says it does?
The cited source says what the claim attributes to it.
In the citing paper
“Their regression results show that entropy has higher explanatory power for the expected return than the capital asset pricing model (CAPM) beta and the standard deviation.”
From Methods and Analysis of Collar Strategies (2021) · cites this paper as Ormos & Zibriczky (2014)
Self-check
Percentages, sums and reported differences re-computed from the paper’s own numbers.
The self-check needs the paper’s full text.
Citations
Cites
A Mathematical Theory of Communication
Shannon, C. E. (1948) · Bell System Technical Journal · doi:10.1002/j.1538-7305.1948.tb01338.x · Cited by 88,486
A Mathematical Theory of Communication
Shannon, C. E. (1948) · The MIT Press eBooks · doi:10.1002/j.1538-7305.1948.tb00917.x · Cited by 50,398
CAPITAL ASSET PRICES: A THEORY OF MARKET EQUILIBRIUM UNDER CONDITIONS OF RISK*
Sharpe, W. F. (1964) · The Journal of Finance · doi:10.1111/j.1540-6261.1964.tb02865.x · Cited by 19,441
Markowitz, H. M. (1952) · The Journal of Finance · doi:10.1111/j.1540-6261.1952.tb01525.x · Cited by 18,429
Density Estimation for Statistics and Data Analysis
Silverman, B. W. (2018) · Routledge eBooks · doi:10.1201/9781315140919 · Cited by 15,938
Density Estimation for Statistics and Data Analysis
(1986) · Springer eBooks · doi:10.1007/978-1-4899-3324-9 · Cited by 8,569
THE PERFORMANCE OF MUTUAL FUNDS IN THE PERIOD 1945–1964
Jensen, M. C. (1968) · The Journal of Finance · doi:10.1111/j.1540-6261.1968.tb00815.x · Cited by 4,332
On Measures of Entropy and Information
Rényi, A. (1961) · Project Euclid (Cornell University) · Cited by 4,031
On Optimal and Data-Based Histograms
Scott, D. W. (1979) · Biometrika · doi:10.1093/biomet/66.3.605 · Cited by 1,875
On the histogram as a density estimator:L 2 theory
Freedman, D. A., & Diaconis, P. W. (1981) · Probability Theory and Related Fields · doi:10.1007/bf01025868 · Cited by 1,693
Research works printed but not linked: 1
- Turlach BA (1993) Bandwidth selection in kernel density estimation: A review: Université catholique de Louvain. DOI: 10.1.1.44.6770.
Cited by
Sorted by citations
Naffa, H., & Fain, M. (2020) · PLoS ONE · doi:10.1371/journal.pone.0244225 · Cited by 94
Foreign exchange rate entropy evolution during financial crises
Stošić, D., Stošić, D., Ludermir, T. B., de Oliveira, W. R., & Stošić, T. (2016) · Physica A Statistical Mechanics and its Applications · doi:10.1016/j.physa.2015.12.124 · Cited by 52
A weighted information-gain measure for ordinal classification trees
Singer, G., Anuar, R., & Ben‐Gal, I. (2020) · Expert Systems with Applications · doi:10.1016/j.eswa.2020.113375 · Cited by 42
Binary and multi-class motor imagery using Renyi entropy for feature extraction
Kee, C.-Y., Ponnambalam, S. G., & Loo, C. K. (2016) · Neural Computing and Applications · doi:10.1007/s00521-016-2178-y · Cited by 36
Information measure for financial time series: Quantifying short-term market heterogeneity
Ponta, L., & Carbone, A. (2018) · Physica A Statistical Mechanics and its Applications · doi:10.1016/j.physa.2018.06.085 · Cited by 29
Hall, M. G., & Clark, C. A. (2016) · Magnetic Resonance in Medicine · doi:10.1002/mrm.26469 · Cited by 29
Information Flow Between Bitcoin and Other Financial Assets
Park, S., Jang, K., & Yang, J. (2020) · Physica A Statistical Mechanics and its Applications · doi:10.1016/j.physa.2020.125604 · Cited by 27
Shannon Entropy: An Econophysical Approach to Cryptocurrency Portfolios
Rodríguez, N. O. R., & Miramontes, O. (2022) · Entropy · doi:10.3390/e24111583 · Cited by 20
Long-Range Dependence in Financial Markets: A Moving Average Cluster Entropy Approach
Murialdo, P., Ponta, L., & Carbone, A. (2020) · Entropy · doi:10.3390/e22060634 · Cited by 20
Elbatal, I., Diab, L. S. G., Ghorbal, A. B., Yousof, H. M., Elgarhy, M., & Ali, E. I. A. (2024) · AIMS Mathematics · doi:10.3934/math.2024350 · Cited by 19
Stock Selection for Portfolios Using Expected Utility-Entropy Decision Model
Yang, J., Feng, Y., & Wan-hua, Q. (2017) · Entropy · doi:10.3390/e19100508 · Cited by 17
The End of Mean-Variance? Tsallis Entropy Revolutionises Portfolio Optimisation in Cryptocurrencies
Chortane, S. G., & Naoui, K. (2025) · Journal of risk and financial management · doi:10.3390/jrfm18020077 · Cited by 13
Entropic Data Envelopment Analysis: A Diversification Approach for Portfolio Optimization
Rotella, P., Rocha, L. C. S., Áquila, G., Balestrassi, P. P., Peruchi, R. S., & Lacerda, L. S. (2017) · Entropy · doi:10.3390/e19090352 · Cited by 11
Financial portfolios based on Tsallis relative entropy as the risk measure
Devi, S. (2019) · Journal of Statistical Mechanics Theory and Experiment · doi:10.1088/1742-5468/ab3bc5 · Cited by 10
Ponta, L., Murialdo, P., & Carbone, A. (2021) · Physica A Statistical Mechanics and its Applications · doi:10.1016/j.physa.2021.125777 · Cited by 10
Friendship of Stock Market Indices: A Cluster-Based Investigation of Stock Markets
Nagy, L., & Ormos, M. (2018) · Journal of risk and financial management · doi:10.3390/jrfm11040088 · Cited by 10
Self-citationRGAN: Rényi Generative Adversarial Network
Sarraf, A., & Nie, Y. (2021) · SN Computer Science · doi:10.1007/s42979-020-00403-9 · Cited by 8
RETRACTED: Entropy-based financial asset pricing: Evidence from Pakistan
Wang, S., Khan, S. A., Munir, M., Alhajj, R., & Khan, Y. A. (2022) · PLoS ONE · doi:10.1371/journal.pone.0278236 · Cited by 7
RetractedApplying Information Theory to Design Optimal Filters for Photometric Redshifts
Kalmbach, J. B., VanderPlas, J. T., & Connolly, A. J. (2020) · The Astrophysical Journal · doi:10.3847/1538-4357/ab684f · Cited by 6
Complexity behaviours of agent-based financial dynamics by hetero-distance contact process
Xiao, D., & Wang, J. (2020) · Nonlinear Dynamics · doi:10.1007/s11071-020-05734-z · Cited by 6
Çavdar, Ş. Ç., & Aydın, A. D. (2015) · Journal of risk and financial management · doi:10.3390/jrfm8030337 · Cited by 6
Inferring multi-period optimal portfolios via detrending moving average cluster entropy (a)
Murialdo, P., Ponta, L., & Carbone, A. (2021) · Europhysics Letters (EPL) · doi:10.1209/0295-5075/133/60004 · Cited by 6
Information Entropy Theory and Asset Valuation: A Literature Survey
Chortane, S. G., & Naoui, K. (2022) · International Journal of Accounting Business and Finance · doi:10.55429/ijabf.v2i1.95 · Cited by 5
The Natural Pattern-based Fuzzy Investment System
Cziráki, G., Pataki, L., Vasa, L., Nagy, B., Bringye, B., & Dávid, L. D. (2024) · Journal of Ecohumanism · doi:10.62754/joe.v3i7.4354 · Cited by 5
Minimum Rényi entropy portfolios
Lassance, N., & Vrins, F. D. (2019) · Annals of Operations Research · doi:10.1007/s10479-019-03364-2 · Cited by 5
Hernández-Montoya, A. R., Rodríguez-Martínez, C. M., Rodrı́guez-Achach, M., & Hernández-Enríquez, D. (2022) · Mathematics · doi:10.3390/math10020215 · Cited by 5
Comparing Entropy and Beta as Measures of Risk in Asset Pricing
Deeva, G. (2017) · Acta Universitatis Agriculturae et Silviculturae Mendelianae Brunensis · doi:10.11118/actaun201765061889 · Cited by 5
Information-Theoretic Approaches to Portfolio SelectionPreprint
Lassance, N. (2019) · SSRN Electronic Journal · doi:10.2139/ssrn.3500947 · Cited by 5
Signatures of Extreme Events in Cumulative Entropic Spectrum
Drzazga, E. A., Kaczmarek, A. Z., Kielak, M., Gupta, S., Gnyp, J. T., Pluta, K., Baķ, Z., Szczepanik, P., & Szczęśniak, D. (2025) · Entropy · doi:10.3390/e27040410 · Cited by 4
Scaling analysis of price by multi-scale Shannon entropy
Osoolian, M., Fadaeinejad, M. E., Bagheri, M., & Ardalankia, J. (2022) · International Journal of Modern Physics C · doi:10.1142/s0129183123500389 · Cited by 4
Chiew, D., Qiu, J., Treepongkaruna, S., Yang, J., & Shi, C. (2019) · PLoS ONE · doi:10.1371/journal.pone.0215320 · Cited by 4
Moroke, N. D., & Metsileng, L. D. (2026) · Mathematics · doi:10.3390/math14183428 · Cited by 3
Entropy Approach for Volatility of Ethereum and Bitcoin
Karakaş, A. M. (2019) · Asian Journal of Business and Management · doi:10.24203/ajbm.v7i1.5682 · Cited by 3
Entropy approach for volatility of wind energy
Çalık, S., & Karakaş, A. M. (2019) · Thermal Science · doi:10.2298/tsci190101346c · Cited by 3
Volatility measurement of the world indices using different entropy methods
Karakaş, A. M. (2019) · Thermal Science · doi:10.2298/tsci190130345m · Cited by 3
Entropy Augmented Asset Pricing Model: Study on Indian Stock Market
Mishra, H., & Barai, P. (2023) · Asia-Pacific Financial Markets · doi:10.1007/s10690-023-09407-w · Cited by 3
Kullback-Leibler cluster entropy to quantify volatility correlation and risk diversity
Ponta, L., & Carbone, A. (2025) · Physical review. E · doi:10.1103/physreve.111.014311 · Cited by 3
Combining Expected Utility and Weighted Gini-Simpson Index into a Non-Expected Utility Device
Casquilho, J. P. (2015) · Theoretical Economics Letters · doi:10.4236/tel.2015.52023 · Cited by 3
Singvejsakul, J., Chaiboonsri, C., & Sriboonchitta, S. (2018) · Journal of Physics Conference Series · doi:10.1088/1742-6596/1053/1/012123 · Cited by 3
An Entropy-Based Cross-Efficiency under Variable Returns to Scale
Su, C.-H., & Lu, T. (2019) · Entropy · doi:10.3390/e21121205 · Cited by 3
Papaioannou, G. P., Dikaiakos, C. N., Dramountanis, A., Georgiadis, D., & Papaioannou, P. G. (2017) · RePEc: Research Papers in Economics · doi:10.48550/arxiv.1711.10552 · Cited by 3
Minimum Rényi Entropy PortfoliosPreprint
Lassance, N., & Vrins, F. D. (2017) · SSRN Electronic Journal · doi:10.2139/ssrn.2968660 · Cited by 3
Performance of Portfolios Based on the Expected Utility-Entropy Fund Rating Approach
Chiew, D., Qiu, J., Treepongkaruna, S., Yang, J., & Shi, C. (2021) · Entropy · doi:10.3390/e23040481 · Cited by 2
Explaining stock return distributions via an agent-based model
Seedat, S., & Abelman, S. (2021) · Nonlinear Dynamics · doi:10.1007/s11071-021-06566-1 · Cited by 2
Comparison between Information Theoretic Measures to Assess Financial Markets
Batra, L., & Taneja, H. C. (2022) · FinTech · doi:10.3390/fintech1020011 · Cited by 2
The Case of “Less is More”: Modelling Risk-Preference with Expected Downside Risk
Ormos, M., & Timotity, D. (2017) · The B E Journal of Theoretical Economics · doi:10.1515/bejte-2016-0100 · Cited by 2
Self-citationEntropies and their Asymptotic Theory in the discrete casePreprint
Ba, A. D., & Lô, G. S. (2019) · arXiv (Cornell University) · doi:10.48550/arxiv.1903.08645 · Cited by 2
Market Volatility, Beta, and Risks in Emerging Markets
Nagy, L. J., Ormos, M., & Timotity, D. (2017) · Contributions to economics · doi:10.1007/978-3-319-47021-4_36 · Cited by 1
Self-citationA Robust Method for Ordering Performances of Multi-assets, Based Purely on Their Return Series
Tulunay, I. (2017) · Journal of Mathematics and System Science · doi:10.17265/2159-5291/2017.11.003 · Cited by 1
Marasović, B., Kalinić, T., & Jerković, I. (2020) · Advances in finance, accounting, and economics book series · doi:10.4018/978-1-7998-5083-0.ch001 · Cited by 1
Mathematical Finance with Applications
Wong, W.-K., Guo, X., & Lozza, S. O. (2020) · MDPI eBooks · doi:10.3390/books978-3-03943-574-6 · Cited by 1
Wybrane metody dywersyfikacji portfeli inwestycyjnych
Gluzicka, A. (2018) · Prace Naukowe / Uniwersytet Ekonomiczny w Katowicach · Cited by 1
Quantifying horizon dependence of asset prices: a cluster entropy approachPreprint
Ponta, L., & Carbone, A. (2019) · RePEc: Research Papers in Economics · doi:10.48550/arxiv.1908.00257 · Cited by 1
Methods and Analysis of Collar Strategies
El-Hassan, N., Hall, A., & Tulunay, I. (2021) · Journal of Applied Business and Economics · doi:10.33423/jabe.v23i8.4882
A Produção do Conhecimento na Engenharia Elétrica 2
Holzmann, H. A., Dallamuta, J., & Granza, M. H. (2020) · doi:10.22533/at.ed.652202303
Barcelos, A. D. S., & Mazzoni, F. M. (2019) · Anais do 14º Simpósio Brasileiro de Automação Inteligente · doi:10.17648/sbai-2019-111165
Gomes, D. C. D. S., & Serra, G. L. D. O. (2020) · doi:10.22533/at.ed.65220230318
dos Santos, M. J., Junior, V. A. F., Granza, M. H., & Lopes, J. L. D. (2020) · doi:10.22533/at.ed.6522023031
Junior, V. A. F., Granza, M. H., & Lopes, J. L. D. (2020) · doi:10.22533/at.ed.65220230311
SISTEMA ESPECIALISTA PARA AVALIAÇÃO DE ENGENHARIA COGNITIVA EM SERIOUS GAMES
Binatti, M. G., de Araújo, M. V. C., & Mustaro, P. N. (2020) · doi:10.22533/at.ed.65220230317
To Reduce Gross NPA and Classify Defaulters Using Shannon Entropy
Sonavane, N., Moharil, A., Kedia, C., & Anand, M. S. (2021) · Algorithms for intelligent systems · doi:10.1007/978-981-33-4893-6_16
de Lima, D. A. C., Silva, H. A., Silva, A. C., Júnior, M. J. A., Cardoso, A., & Júnior, E. A. L. (2020) · doi:10.22533/at.ed.6522023037
MODELAGEM INTELIGENTE NEBULOSA APLICADA À HIDROPONIA VIA SISTEMA EMBARCADO
Lopes, K. V. L., Pires, D. S., & Filho, O. D. R. (2020) · doi:10.22533/at.ed.65220230314
Performance of Portfolios Based on the Expected Utility-Entropy Fund Rating Approach
Chiew, D., Qiu, J., Treepongkaruna, S., Yang, J., & Shi, C. (2019) · International Electronic Conference on Entropy and Its Applications (ECEA) · doi:10.3390/ecea-5-06679
DESENVOLVIMENTO DE UMA ESTRUTURA DE CONTROLE HÍBRIDA PARA SISTEMAS DE REFRIGERAÇÃO DE ALTA PRESSÃO
Vitor, M. F., Silveira, A. D. S., Matias, G., & Flesch, R. C. C. (2020) · doi:10.22533/at.ed.6522023039
MODELO DE NEURÔNIO MEMRISTIVO DE DIÓXIDO DE VANÁDIO COM CODIFICAÇÃO DE IMPULSOS PRBS-PWM
de Araujo, R. S., de Almeida, L. A. L., & da Costa, F. S. O. (2020) · doi:10.22533/at.ed.65220230315
To Reduce Gross NPA and Classify Defaulters Using Shannon EntropyPreprint
Moharil, A., Sonavane, N., Kedia, C., & Anand, M. S. (2020) · arXiv (Cornell University) · doi:10.48550/arxiv.2004.14418
The Lexical Ratio: A New Perspective on Portfolio DiversificationPreprint
Mohseni, S. F., Arian, H. R., & Bégin, J. (2025) · SSRN Electronic Journal · doi:10.2139/ssrn.5014869
The lexical ratio: a new perspective on portfolio diversification
Mohseni, S. F., Arian, H. R., & Bégin, J. (2025) · Financial markets and portfolio management · doi:10.1007/s11408-025-00478-5
Level of Service Analysis of a Bus Route Considering Headway and CrowdingPreprint
Devasurendra, K. W., Wirasinghe, S. C., & Kattan, L. (2025) · SSRN Electronic Journal · doi:10.2139/ssrn.5675596
Level of Service Measures for an Urban Bus Route
Wimalasiri Devasurendra, K. (2023) · doi:10.11575/prism/41592
(2026) · Pesci Egyetemi Archivum (University of Pécs) · doi:10.15170/xviippn-tk-ktk-2026
FUZZY-ENTRÓPIA-ALAPÚ KOCKÁZATOSSÁGI MUTATÓ: EMPIRIKUS KONSTRUKCIÓ ÉS ALKALMAZÁS
Fáró, J., & Jónás, T. (2026) · doi:10.15170/xviippn-tk-ktk-2026-05
A Reproducible Stability Audit of Multi-Criteria ETF Ranking for FinTech Decision Support
Yao, J. (2026) · Empirical Studies in Econimics and Finance · doi:10.70693/jg0sfa24
A quarter century after the 1997 Asian crisis: Looking back, where are we now?
Günay, S., Juhász, P., & Naffa, H. (2026) · Asia and the Global Economy · doi:10.1016/j.aglobe.2026.100149
Metadata
- Authors
- Ormos, M., & Zibriczky, D.
- Affiliations
- Budapest University of Technology and Economics (HU)
- Corresponding author
- Ormos, Mihály
- ORCID
- Ormos, Mihály
- Venue
- PLoS ONE
- Publisher
- Public Library of Science (PLoS)
- Published
- 2014-12-29
- Volume
- 9
- Issue
- 12
- Pages
- e115742
- ISSN
- 1932-6203 (ISSN-L)
- PMC
- PMC4278763
- OpenAlex
- W1964018898
- Cited by
- 70
- References
- 24
- Citations by year
- 2026: 2 · 2025: 6 · 2024: 1 · 2023: 1 · 2022: 6 · 2021: 7 · 2020: 17 · 2019: 12 · 2018: 4 · 2017: 9 · 2016: 3 · 2015: 2
- FWCI
- 8.54
- Type
- journal article
- Language
- en
- Open access
- gold
- doi.org
- Locations
- PLoS ONE (publishedVersion, cc-by)
- Europe PMC (PubMed Central) (publishedVersion, cc-by)
- PubMed Central (publishedVersion, cc-by)
- PubMed (publishedVersion)
- arXiv (Cornell University) (submittedVersion)
- RePEc: Research Papers in Economics (submittedVersion)
- DOAJ (DOAJ: Directory of Open Access Journals) (submittedVersion, cc-by-sa)
- Figshare (submittedVersion, cc-by)
- Topics
- Social Sciences › Economics, Econometrics and Finance › Finance › Financial Markets and Investment Strategies
- Social Sciences › Economics, Econometrics and Finance › Finance › Financial Risk and Volatility Modeling
- Social Sciences › Decision Sciences › Management Science and Operations Research › Risk and Portfolio Optimization
- Keywords
- entropy (information theory), asset pricing, equity premium, capital asset pricing model, beta, efficient frontier, expected returns, portfolio diversification, time-varying beta, daily stock returns
- MeSH terms
- Costs and Cost Analysis, Investments, Models, Theoretical, Risk Factors, Entropy
About these checks
Registry, retraction, Cites and statistics results are computed, not judged, with one exception: a printed reference that no index lists is read once by a model before it counts as a citation error. Claims are extracted by a model and kept only when their quote appears verbatim in the text; each cited source is then checked, with a model’s help, for whether it says what the claim relies on. Those verdicts can be wrong — read the claim’s quote and the cited source before relying on one.
Statistics and arithmetic are recomputed, not judged.
Confidence bands are shown only for fields calibrated on our annotated test set. None is calibrated yet, so no band is shown.
What counts as a claim ›How we measure confidence ›How we check this ›
Are you an author, or do you see a problem with this page? Request a review
