

The DOI matches its Crossref record.
Within and Cross Volatility Contagion Effects among Stock, Crude and Forex Returns: Empirical Evidence from Five Emerging Economies
Open accessAbstract
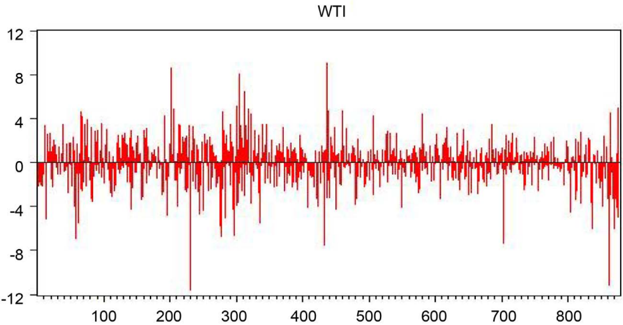
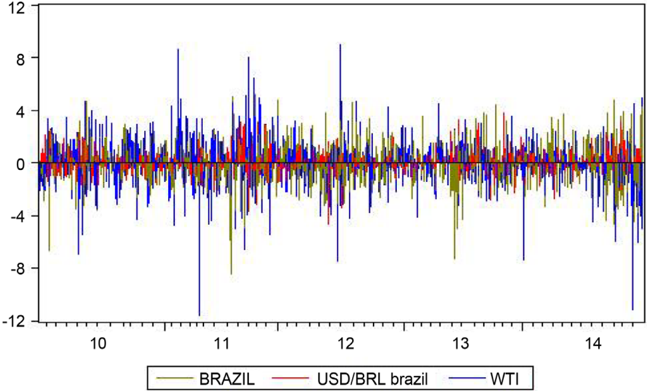
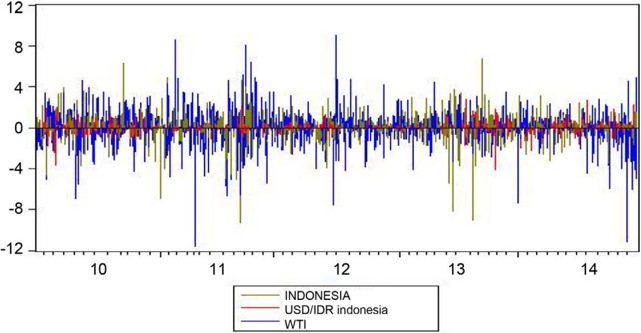
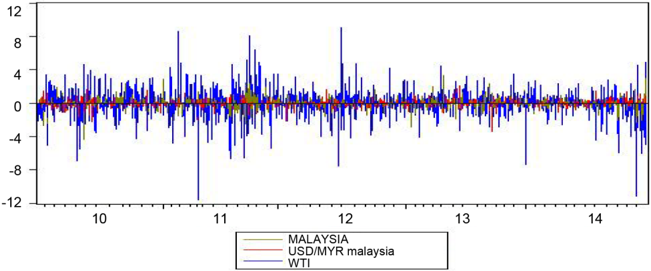
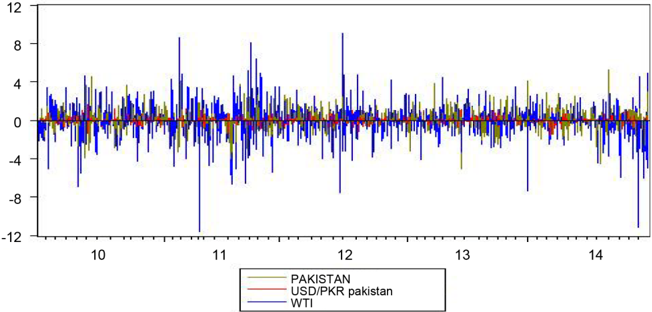
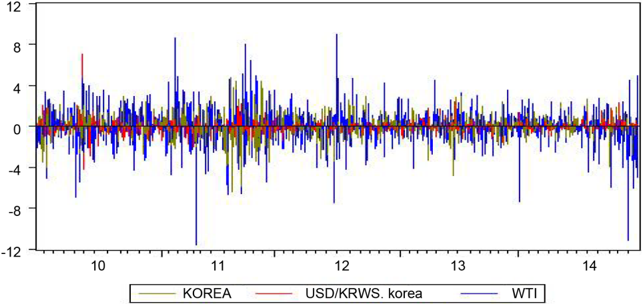
The paper examines the spillover effects of return volatility among stock market index, foreign exchange market and WTI crude oil market across five emerging nations. Here a Trivariate Diagonal BEKK-GARCH model is used to estimate the time-varying conditional variance and to test the own-volatility spillover effects of returns among the three underlying variables. We find that significant own volatility spillover exists in the WTI returns followed by that of stock returns and forex returns. Further, fluctuations in WTI returns exert considerable influence over the stock market volatilities. The lagged variance of the variables as well as their lagged squared residuals from the mean equation has a positive and significant impact on the current volatility in most cases. The findings of the study are of pertinent importance to financiers, economists, investors and policymakers.
Overview
The claims and statistics of this paper haven’t been checked yet.
Run the check — free, no account needed. It reads the open-access text and checks the sources it cites.
Integrity signals
Registry
Cites
Statistics
Figures
Verification
Claims the paper makes
The claims and statistics of this paper haven’t been checked yet.
Run the check — free, no account needed. It reads the open-access text and checks the sources it cites.
Self-check
Percentages, sums and reported differences re-computed from the paper’s own numbers.
The self-check needs the paper’s full text.
Citations
Cites
No references could be resolved yet.
Research works printed but not linked: 13
- Apte, P.G. (1997) Currency Exposure and Stock Prices. Journal of Foreign Exchange and International Finance, 12, 135-143.
- 10.1111/j.1540-6261.1994.tb04780.x · DOI
- Wang, M.L., Wang, C.P. and Huang, T.Y. (2010) Relationships among Oil Price, Gold Price, Exchange Rate and International Stock Markets. International Research Journal of Finance and Economics, 47, 80-89.
- 10.1016/j.apenergy.2010.10.043 · DOI
- Adebiyi, M.A., Adenuga, A.O., Abeng, M.O. and Omanukwue, P.N. (2009) Oil Price Shocks, Exchange Rate and Stock Market Behaviour: Empirical Evidence from Nigeria. Proceedings of the 14th Annual Conference of the African Econometric Society.
- Aydemir, O. and Demirhan, E. (2009) The Relationship between Stock Prices and Exchange Rates: Evidence from Turkey. International Research Journal of Finance and Economics, 23, 207-215.
- 10.1093/rfs/14.1.215 · DOI
- 10.2307/2331212 · DOI
- 10.1111/0022-1082.295575 · DOI
- 10.1016/S0378-4266(97)00002-2 · DOI
- 10.1111/j.1468-5957.1990.tb01196.x · DOI
- 10.1111/j.1475-6803.1996.tb00593.x · DOI
- 10.1080/096031097333826 · DOI
Cited by
Sorted by citations
Ali, P. (2022) · AFRE (Accounting and Financial Review) · doi:10.26905/afr.v5i1.7547 · Cited by 1
Metadata
- Authors
- Varghese, G.
- Affiliations
- IFMR Graduate School of Business (IN)
- Corresponding author
- Varghese, George
- ORCID
- Varghese, George
- Venue
- Theoretical Economics Letters
- Publisher
- Scientific Research Publishing, Inc.
- Published
- 2018
- Volume
- 08
- Issue
- 08
- Pages
- 1475-1492
- ISSN
- 2162-2078 (ISSN-L)
- 2162-2086
- OpenAlex
- W2806739678
- Cited by
- 3
- References
- 0
- Citations by year
- 2022: 1 · 2021: 1 · 2020: 1
- FWCI
- 0.66
- Type
- journal article
- Language
- en
- Open access
- diamond
- doi.org
- Locations
- Theoretical Economics Letters (publishedVersion, cc-by)
- Topics
- Social Sciences › Economics, Econometrics and Finance › Finance › Financial Risk and Volatility Modeling
- Social Sciences › Economics, Econometrics and Finance › Economics and Econometrics › Market Dynamics and Volatility
- Social Sciences › Economics, Econometrics and Finance › Economics and Econometrics › COVID-19 Pandemic Impacts
- Keywords
- volatility spillovers, volatility contagion, stock market volatility, oil prices, WTI crude oil, exchange rate returns, emerging markets, cross-market linkages
About these checks
Registry, retraction, Cites and statistics results are computed, not judged, with one exception: a printed reference that no index lists is read once by a model before it counts as a citation error. Claims are extracted by a model and kept only when their quote appears verbatim in the text; each cited source is then checked, with a model’s help, for whether it says what the claim relies on. Those verdicts can be wrong — read the claim’s quote and the cited source before relying on one.
Statistics and arithmetic are recomputed, not judged.
Confidence bands are shown only for fields calibrated on our annotated test set. None is calibrated yet, so no band is shown.
What counts as a claim ›How we measure confidence ›How we check this ›
Are you an author, or do you see a problem with this page? Request a review
How to cite
Cite CoChat for the checks on this page, and the paper for its own findings.
- This page
- CoChat. (2026). Citation check: Within and Cross Volatility Contagion Effects among Stock, Crude and Forex Returns: Empirical Evidence from Five Emerging Economies. https://app.cochat.ai/papers/10.4236/tel.2018.88095
- The paper
- Varghese, G. (2018). Within and Cross Volatility Contagion Effects among Stock, Crude and Forex Returns: Empirical Evidence from Five Emerging Economies. Theoretical Economics Letters. https://doi.org/10.4236/tel.2018.88095
