

The DOI matches its Crossref record; 2 of the 2 references it cites were found in a registry or an index.
Artificial Intelligence Applied to Stock Market Trading: A Review
Overview
The claims and statistics of this paper haven’t been checked yet.
Run the check — free, no account needed. It reads the open-access text and checks the sources it cites.
Integrity signals
Registry
Cites
Statistics
Figures
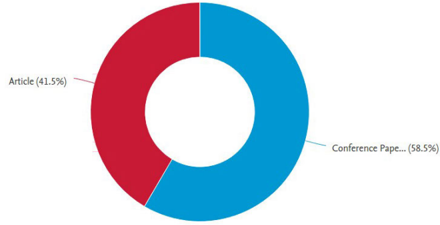
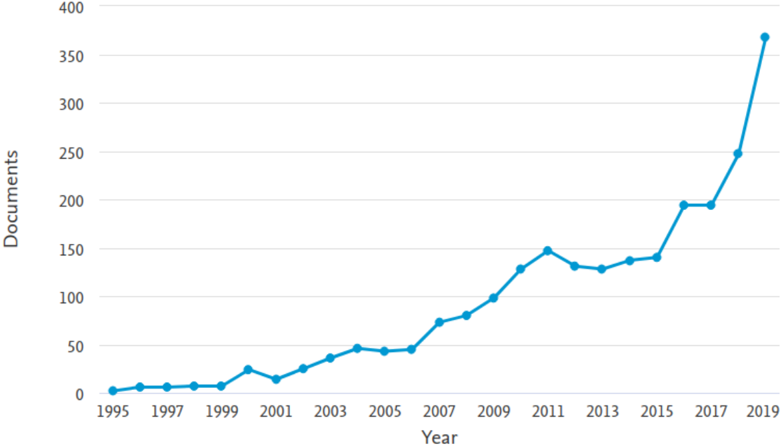
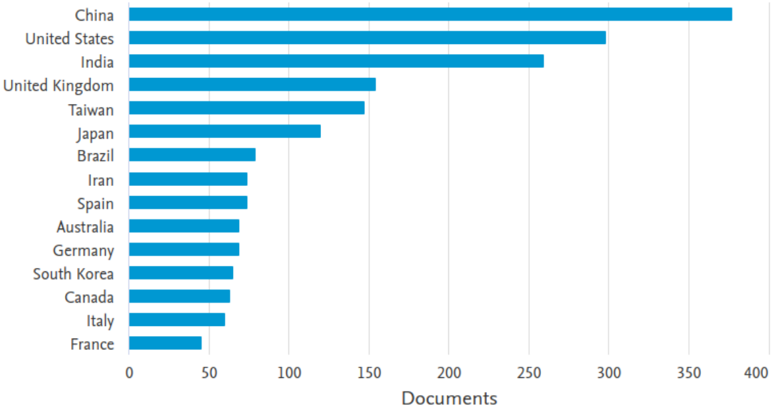
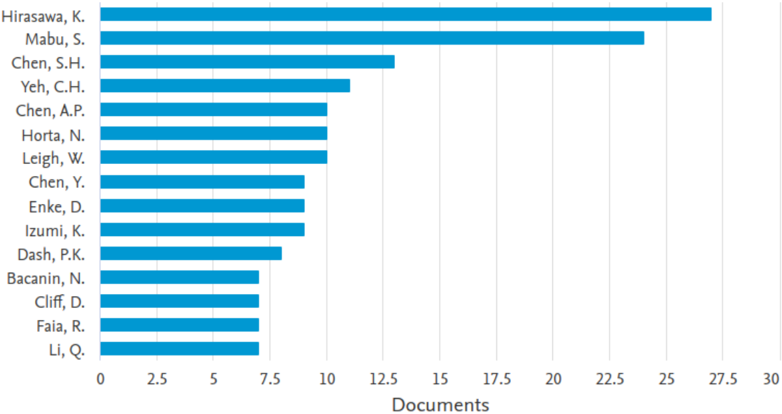
Verification
Claims the paper makes
The claims and statistics of this paper haven’t been checked yet.
Run the check — free, no account needed. It reads the open-access text and checks the sources it cites.
Claims other papers make about this one
Each is checked against this paper’s own text: does it say what the citing paper says it does?
In the citing paper
“From business communication systems and financial trading networks to smart energy grids and logistical networks (Camacho et al., 2024; Ferreira et al., 2021; Mayorkas, 2024), entities or communication channels that were once controlled by humans are increasingly becoming AI-powered.”
From Multi-Agent Risks from Advanced AI (2025) · cites this paper as Ferreira et al., 2021
Self-check
Percentages, sums and reported differences re-computed from the paper’s own numbers.
The self-check needs the paper’s full text.
Citations
Cites
Twitter mood predicts the stock market
Bollen, J., Mao, H., & Zeng, X. (2011) · Journal of Computational Science · doi:10.1016/j.jocs.2010.12.007 · Cited by 5,206
Automated trading with performance weighted random forests and seasonality
Booth, A., Gerding, E., & McGroarty, F. (2014) · Expert Systems with Applications · doi:10.1016/j.eswa.2013.12.009 · Cited by 154
Research works printed but not linked: 95
- 10.1023/A:1008768404046 · DOI
- 10.1016/j.eswa.2006.08.001 · DOI
- 10.1007/s00521-011-0721-4 · DOI
- 10.1016/j.eswa.2011.04.210 · DOI
- 10.1145/1389095.1389387 · DOI
- 10.1016/j.dss.2013.02.006 · DOI
- 10.1016/j.physa.2009.03.028 · DOI
- 10.1016/j.cor.2004.03.016 · DOI · Paper page
- 10.1016/j.eswa.2007.11.062 · DOI
- 10.1016/j.eswa.2007.05.035 · DOI · Paper page
- 10.1109/CIFER.1995.495230 · DOI
- 10.1016/j.dss.2013.09.013 · DOI
- 10.1016/j.knosys.2010.05.004 · DOI
- 10.1023/B:ANOR.0000039513.99038.c6 · DOI
- 10.1016/j.eswa.2005.06.024 · DOI
- 10.1016/S0377-2217(02)00881-0 · DOI
- 10.1016/j.cor.2005.06.017 · DOI
- 10.1016/j.swevo.2018.01.009 · DOI
- 10.1016/j.ejor.2017.11.054 · DOI
- mendonça, 2020, Multi-attribute decision making applied to financial portfolio optimization problem, Expert Syst Appl, 158, 10.1016/j.eswa.2020.113527 · DOI
- lo, 2007, Efficient markets hypothesis, The New Palgrave Dictionary of Economics
- 10.1016/j.knosys.2018.10.034 · DOI
- 10.3390/e22080840 · DOI
- murphy, 1999, Technical Analysis of the Financial Markets A Comprehensive Guide to Trading Methods and Applications
- 10.1109/CEC.2006.1688603 · DOI
- 10.1109/BigDataService.2019.00035 · DOI
- 10.1109/HICSS.2004.1265201 · DOI
- 10.2307/2975974 · DOI
- 10.1016/j.ejor.2013.08.035 · DOI
- 10.1016/S0377-2217(98)00252-5 · DOI
- 10.1016/j.eswa.2017.05.018 · DOI
- 10.1007/978-981-10-8201-6_5 · DOI
- 10.1016/j.knosys.2012.05.003 · DOI
- 10.1016/j.csda.2004.02.004 · DOI
- 10.1109/ICOMET.2018.8346382 · DOI
- 10.1142/S0129065797000409 · DOI
- 10.2200/S00416ED1V01Y201204HLT016 · DOI
- 10.1016/j.cor.2005.01.027 · DOI
- 10.3390/app9173509 · DOI
- 10.1016/S0169-2070(98)00003-X · DOI
- 10.1016/j.knosys.2014.04.022 · DOI
- 10.1016/S0165-0114(98)00399-6 · DOI
- 10.1016/j.eswa.2010.10.027 · DOI
- kansal, 2019, Optimized feature extraction based artificial 1301 intelligence technique for empirical analysis of stock market data, Int J Innov Technol Exploring Eng, 8, 10.35940/ijitee.J8837.0881019 · DOI
- 10.1016/j.eswa.2005.09.020 · DOI
- 10.1186/s40854-019-0140-6 · DOI
- 10.1109/MC.2010.2 · DOI
- 10.1109/CIFER.1996.501826 · DOI
- 10.1016/j.knosys.2018.01.016 · DOI
- 10.1016/j.knosys.2019.03.029 · DOI
- 10.1016/j.eswa.2019.05.018 · DOI
- 10.5267/j.msl.2015.7.003 · DOI
- 10.1145/1462198.1462204 · DOI
- 10.1007/s11771-016-3061-9 · DOI
- smailovi?, 2013, Predictive sentiment analysis of Tweets A stock market application, 7947, 77
- 10.1016/0305-0548(95)00030-5 · DOI
- 10.1016/j.eswa.2015.07.052 · DOI
- pagolu, 2017, Sentiment analysis of Twitter data for predicting stock market movements, Proc Int Conf Signal Process Commun Power Embedded Syst, 1345
- 10.1016/j.dss.2016.02.013 · DOI
- 10.1016/j.eswa.2014.07.040 · DOI · Paper page
- 10.1016/j.epsr.2010.05.006 · DOI
- 10.1109/TEVC.2012.2196800 · DOI
- 10.1016/S0305-0548(03)00063-7 · DOI
- 10.1109/JSYST.2018.2794462 · DOI
- 10.1016/S0378-4266(02)00271-6 · DOI
- 10.1080/00036846.2018.1564115 · DOI
- 10.21314/JOR.2000.038 · DOI · Paper page
- 10.1016/j.eswa.2013.08.028 · DOI
- 10.1109/MCI.2018.2866727 · DOI
- 10.1186/s40854-019-0138-0 · DOI
- 10.1109/IJCNN.1999.830772 · DOI
- 10.1007/s12559-018-9609-2 · DOI
- 10.1016/j.ejor.2012.04.023 · DOI
- zadrozny, 2019, A comparison of neural network methods for accurate sentiment analysis of stock market tweets, Proc ECML PKDD Workshops MIDAS PAP, 11054, 51
- tsai, 2017, The information content of implied volatility skew: Evidence on Taiwan stock index options, Data Sci Pattern Recognit, 1, 48
- 10.1016/j.eswa.2011.02.075 · DOI
- 10.1002/spe.2915 · DOI
- 10.1016/j.eswa.2016.02.006 · DOI
- chang, 2018, How A I Traders Will Dominate Hedge Fund Industry
- 10.1016/S0305-0548(99)00074-X · DOI
- 10.1016/j.eswa.2009.02.062 · DOI
- 10.1007/s10878-018-0364-9 · DOI
- 10.1016/j.physa.2015.02.060 · DOI
- 10.1016/j.eswa.2017.04.030 · DOI · Paper page
- 10.1109/CEC.2005.1554896 · DOI
- 10.1016/S0377-2217(02)00784-1 · DOI
- takahashi, 2007, Analysis of the Relation Between Stock Price Returns and Headline News Using Text Categorization, 4693, 1339
- 10.1016/j.eswa.2018.08.003 · DOI
- takahashi, 2006, Analysis of Stock Price Return Using Textual Data and Numerical Data Through Text Mining, 4252, 310
- 10.1016/S0377-2217(02)00774-9 · DOI
- 10.1109/ICSMC.1998.725072 · DOI
- 10.36713/epra4361 · DOI
- 10.1016/j.neucom.2011.12.013 · DOI
- 10.1016/S0957-4174(01)00047-1 · DOI
- 10.1016/S0957-4174(02)00079-9 · DOI
Cited by
Sorted by citations
Weber, P., Carl, K. V., & Hinz, O. (2024) · Management Review Quarterly · doi:10.1007/s11301-023-00320-0 · Cited by 292
“Trading in the stock market benefits from AI usage, as the latter is expected to impede emotionally, and thus irrational, investment decisions and find patterns beyond human recognizability (Ferreira et al. 2021).”
Multi-Agent Risks from Advanced AI
Hammond, L., Chan, A., Clifton, J., Hoelscher-Obermaier, J., Khan, A., McLean, E., Smith, C., Barfuss, W., Foerster, J., Gavenčiak, T., et al. (2025) · arXiv · doi:10.48550/arxiv.2502.14143 · Cited by 305
Metadata
- Authors
- Ferreira, F. G. D. C., Gandomi, A. H., & Cardoso, R. T. N.
- Affiliations
- Department of Mathematical and Computational Modeling, Centro Federal de Educação Tecnológica de Minas Gerais, Belo Horizonte, Brazil
- Faculty of Engineering and Information Technology, University of Technology Sydney, Sydney, NSW, Australia
- Venue
- IEEE Access
- Published
- 2021
- Volume
- 9
- Pages
- 30898-30917
- ISSN
- 2169-3536
- Cited by
- 187
- References
- 2
- Funders
- Coordenação de Aperfeiçoamento de Pessoal de Nível Superior - Brasil (001 (Proc. 88881.361790/2019-01))
About these checks
Registry, retraction, Cites and statistics results are computed, not judged, with one exception: a printed reference that no index lists is read once by a model before it counts as a citation error. Claims are extracted by a model and kept only when their quote appears verbatim in the text; each cited source is then checked, with a model’s help, for whether it says what the claim relies on. Those verdicts can be wrong — read the claim’s quote and the cited source before relying on one.
Statistics and arithmetic are recomputed, not judged.
Confidence bands are shown only for fields calibrated on our annotated test set. None is calibrated yet, so no band is shown.
What counts as a claim ›How we measure confidence ›How we check this ›
Are you an author, or do you see a problem with this page? Request a review
