

The DOI matches its Crossref record, with a small difference in title or year; 81 of the 81 references it cites were found in a registry or an index; 4 of the 34 sources its claims cite were checked for support.
Technical trading and cryptocurrencies
Open accessAbstract
This paper carries out a comprehensive examination of technical trading rules in cryptocurrency markets, using data from two Bitcoin markets and three other popular cryptocurrencies. We employ almost 15,000 technical trading rules from the main five classes of technical trading rules and find significant predictability and profitability for each class of technical trading rule in each cryptocurrency. We find that the breakeven transaction costs are substantially higher than those typically found in cryptocurrency markets. To safeguard against data-snooping, we implement a number of multiple hypothesis procedures which confirms our findings that technical trading rules do offer significant predictive power and profitability to investors. We also show that the technical trading rules offer substantially higher risk-adjusted returns than the simple buy-and-hold strategy, showing protection against lengthy and severe drawdowns associated with cryptocurrency markets. However there is no predictability for Bitcoin in the out-of-sample period, although predictability remains in other cryptocurrency markets.
Overview
CoChat Summary
TL;DR
This paper examines almost 15,000 technical trading rules across five cryptocurrency markets—two Bitcoin price series plus Litecoin, Ethereum, and Ripple—and finds significant in-sample predictability and profitability for all five rule classes. After multiple-hypothesis adjustments many rules remain significant and often beat buy-and-hold on risk-adjusted measures, but Bitcoin shows no out-of-sample predictability while the other cryptocurrencies do.
Key findings
- All five technical trading rule classes generate statistically significant average annualized returns in each cryptocurrency at the 5% level; filter and channel breakout rules perform best, with annualized returns as high as 16.45% for Ripple.
- Breakeven transaction costs are often substantially higher than typical cryptocurrency costs: they range from 7.88 basis points for the support-resistance rule in Litecoin to 147.56 basis points for the filter rule in Ethereum, and reach 66.41 and 57.51 basis points for CoinDesk and Bitstamp, respectively.
- Multiple-hypothesis procedures confirm profitability: after Bonferroni, Holm, BH, and BY adjustments, the percentage of rules remaining significant at the 5% level ranges from 20.35% to 50.41% across cryptocurrencies.
- Technical rules offer substantially higher risk-adjusted returns than buy-and-hold and protect against lengthy severe drawdowns, but out-of-sample results show negative annualized returns, Sharpe, and Sortino ratios for both Bitcoin markets, while Litecoin, Ripple, and Ethereum remain positive.
Methods
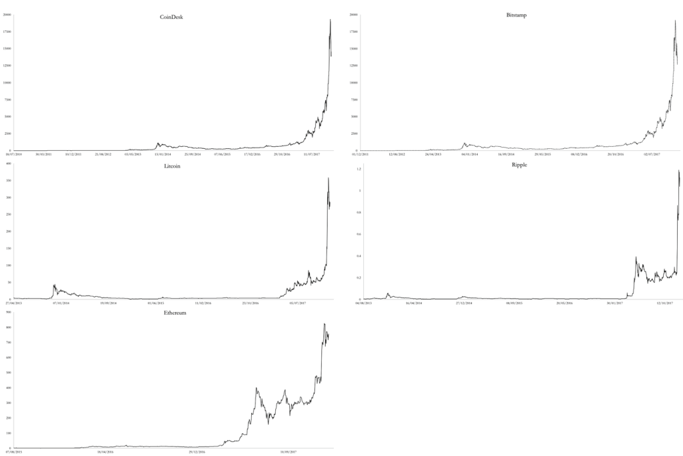
- Daily data from CoinDesk Bitcoin (from 18 July 2010), Bitstamp Bitcoin (from 1 December 2012), Litecoin (from 28 April 2013), Ripple (from 4 August 2013), and Ethereum (from 7 August 2015), all ending 31 December 2017.
- 14,919 technical trading rules from five classes: moving average, filter, support-resistance, oscillator, and channel breakout. Performance is assessed with mean returns, Sharpe, Sortino, Calmar ratios, and breakeven transaction costs, and compared with buy-and-hold.
- Data-snooping controls use stationary bootstrap with 1,000 realizations and block length 0.1 to obtain individual bootstrapped p-values following Sullivan et al. (1999), then Bonferroni, Holm, BH, and BY multiple-hypothesis procedures; out-of-sample tests apply the best in-sample rules to the first six months of 2018.
Limitations
- Stated: transaction costs differ by cryptocurrency and exchange and are difficult to accurately estimate, especially for CoinDesk as an average of exchanges; the paper therefore reports breakeven transaction costs rather than applying a single cost.
- Stated: the choice of in-sample and out-of-sample periods is an issue, and technical trading performance tends to diminish over time and after academic publication; the out-of-sample test covers only the first six months of 2018.
- Evident: the in-sample period ends 31 December 2017 and the out-of-sample window is short, so the findings may not generalize to later cryptocurrency market regimes; the Bonferroni and Holm adjustments are described as very conservative and may understate the number of profitable rules.
Model-written summary. Check it against the paper before relying on it.
Integrity signals
Registry
Cites
Statistics
Figures
Verification
Claims the paper makes
4 Valid · 0 Not valid · 24 Not checked · 85 Own results and interpretations
Every source the paper cites for this claim was checked and supports it.
In the paper
“This is especially important for technical trading rules since there is a trend in the literature for the performance of the rules to diminish over time (Menkhoff 2007).”
What the sources say
- Supportedcites Menkhoff 2007 source
Section 4 (p. 11) says there is evidence that traditional moving-average trading rules became much less profitable from the 1970s to the 1990s, supporting the claimed trend. It also notes exceptions: some complex rules may not have become less profitable, and significant profits remain. (LLM, conf=0.88)
plainstates an association- Asserted: passes — The authors put it forward as true.
- Checkable: passes — It can be checked against evidence.
- Load-bearing: passes — The paper’s conclusions depend on it.
- Based: passes — The paper gives a reason why it holds.
- Supported
The cited sources support only part of this claim — read each source’s verdict below.
In the paper
“This is also reflected in the academic literature where Corbet et al. (2019) show that the majority of academic papers on cryptocurrencies solely focus on Bitcoin.”
What the sources say
- Partly supportedcites Corbet et al. 2019 sourceExperimental — accuracy not yet measured
In the discussion accompanying Figure 2 (page unavailable), the paper reports that Bitcoin was the central cryptocurrency in 74.3% of the papers it analysed. That supports the majority claim for its selected papers, but being the central topic does not establish that those papers focused solely on Bitcoin. (LLM, conf=0.88)
plain- Asserted: passes — The authors put it forward as true.
- Checkable: passes — It can be checked against evidence.
- Load-bearing: unclear — It is unclear whether the paper’s conclusions depend on it.
- Based: passes — The paper gives a reason why it holds.
- Partly supported
The sources with a verdict support this claim; the rest weren’t checked yet, have no full text we could read, or their verdicts aren’t rated yet.
In the paper
“Another solution to address the data-snooping issue is to employ an out-of-sample analysis to examine if the best technical trading rules from the in-sample estimation performs well out of sample (Sullivan et al. 1999; Harvey et al. 2016).”
What the sources say
- Not checked — no full text of the sourcecites Sullivan et al. 1999 source
- Supportedcites Harvey et al. 2016 source
Section 3.1 (‘Why multiple testing?’) identifies out-of-sample validation as one of two ways to address bias from multiple testing and calls it the cleanest way to rule out spurious factors when feasible. It cautions that a genuine out-of-sample test requires future data; simply holding out data already observable to researchers does not qualify. (LLM, conf=0.92)
plainstates a cause- Asserted: passes — The authors put it forward as true.
- Checkable: passes — It can be checked against evidence.
- Load-bearing: passes — The paper’s conclusions depend on it.
- Based: passes — The paper gives a reason why it holds.
A result the paper reports from its own data — it cites no other source for it, so there is none to check. The quote shows it is in the paper.
In the paper
“The breakeven transaction costs range 7.88 basis points for the supportresistance rule in Litecoin to 147.56 basis points for the filter rule in Ethereum.”
plain- Asserted: passes — The authors put it forward as true.
- Checkable: passes — It can be checked against evidence.
- Load-bearing: passes — The paper’s conclusions depend on it.
- Based: passes — The paper gives a reason why it holds.
- Rests on an assumption not shown here.
A result the paper reports from its own data — it cites no other source for it, so there is none to check. The quote shows it is in the paper.
In the paper
“For instance, 36.06% of oscillator rules generate breakeven transaction costs greater than 50 basis points for CoinDesk while 47.35% of channel breakout rules generate rules with breakeven transaction costs greater than 50 basis points for Ethereum.”
plain- Asserted: passes — The authors put it forward as true.
- Checkable: passes — It can be checked against evidence.
- Load-bearing: unclear — It is unclear whether the paper’s conclusions depend on it.
- Based: passes — The paper gives a reason why it holds.
- Rests on an assumption not shown here.
59 more claims
Create a free account to see all 113 claims and every source verdict.
- Probably not a substantial claim. 17
- It may state two separate claims as one. 36
- The quote only partly states this claim. 2
Self-check
Percentages, sums and reported differences re-computed from the paper’s own numbers.
Each contradiction between two passages listed here was confirmed by an independent check.
Rated major: it would touch a result — a value a result rests on, reported and recomputed p-values on opposite sides of the significance level, two passages that conflict with no sign which is right, or a cited work retracted before this paper was published.
In the paper
“MA 2 = # q × # x × # d × # k = 9 × 7 × 5 × 2 = 945”
Reported 945 · recomputed 630
Rated minor: it would not touch a result — a value no result rests on, a p-value that stays on the same side of the significance level, or a conflict that is clerical, resolved elsewhere in the paper, or outside its own findings.
In the paper
§ 6.5 Out-of-sample performance · p. 23
“| CoinDesk | CB2: 25/0.05/0.025/5 | - 0 . 0010 | - 0 . 0502 | - 0 . 3470 | | Bitstamp | CB2: 25/0.05/0.025/3 | - 0 . 0091 | - 0 . 0641 | - 0 . 0553 | | Litecoin | CB2: 25/0.05/0.025/5 | 0 . 0775 | 1 . 3553 | 2 . 1900 | | Ripple | MA1: 2/0.001/1 | 0 . 0546 | 0 . 7380 | 1 . 2162 |”
§ Appendix · p. 26
“x ∈ { 0 , 0 . 01 , 0 . 05 , 0 . 1 , 0 . 5 , 1 , 5 } , # x = 7”
Cited works that were retracted
Works this paper cites that were later retracted, from the retraction notices publishers deposit. Major when the notice came out before this paper was published.
Rated major: it would touch a result — a value a result rests on, reported and recomputed p-values on opposite sides of the significance level, two passages that conflict with no sign which is right, or a cited work retracted before this paper was published.
In the paper
“Corbet, S., Lucey, B., & Yarovaya, L. (2018). Datestamping the bitcoin and ethereum bubbles. Finance Research Letters, 26, 81–88.”
Cited work 10.1016/j.frl.2017.12.006 · retracted 2018-09-01 · notice 10.1016/j.frl.2017.12.006 · this paper published 2019-08-30
A note, not an issue: for example, a cited work that was retracted only after this paper was published, which its authors could not have known.
In the paper
“Corbet, S., Lucey, B., Urquhart, A., & Yarovaya, L. (2019). Cryptocurrencies as a financial asset: A systematic analysis. International Review of Financial Analysis, 62, 182–199.”
Cited work 10.1016/j.irfa.2018.09.003 · retracted 2026-02-01 · notice 10.1016/j.irfa.2026.105078 · this paper published 2019-08-30
Citations
Cites
2 retracted
RETRACTED: Cryptocurrencies as a financial asset: A systematic analysis
Corbet, S., Lucey, B., Urquhart, A., & Yarovaya, L. (2019) · International Review of Financial Analysis · doi:10.1016/j.irfa.2018.09.003 · Cited by 1,172
Self-citationRetractedRETRACTED: Datestamping the Bitcoin and Ethereum bubbles
Corbet, S., Lucey, B., & Yarovaya, L. (2018) · Finance Research Letters · doi:10.1016/j.frl.2017.12.006 · Cited by 638
RetractedControlling the False Discovery Rate: A Practical and Powerful Approach to Multiple Testing
Benjamini, Y., & Hochberg, Y. (1995) · Journal of the Royal Statistical Society Series B: Statistical Methodology · doi:10.1111/j.2517-6161.1995.tb02031.x · Cited by 109,482 · cited 4×
“One of the earliest FDR controlling methods is by Benjamini and Hochberg (1995) and is a stepwise procedure that, assuming all individual p-values are ordered from smallest to largest and defining: j∗ = max { j : p ≤ j × δ M } (7)”
InfluentialThe control of the false discovery rate in multiple testing under dependency
Benjamini, Y., & Yekutieli, D. (2001) · The Annals of Statistics · doi:10.1214/aos/1013699998 · Cited by 10,490
Politis, D. N., & Romano, J. P. (1994) · Journal of the American Statistical Association · doi:10.1080/01621459.1994.10476870 · Cited by 2,649
Simple technical trading rules and the stochastic properties of stock returns
BROCK, W., LAKONISHOK, J., & LeBARON, B. (1992) · The Journal of Finance · doi:10.1111/j.1540-6261.1992.tb04681.x · Cited by 2,301
… and the Cross-Section of Expected Returns
Harvey, C. R., Liu, Y., & Zhu, H. (2016) · Review of Financial Studies · doi:10.1093/rfs/hhv059 · Cited by 2,119
A Reality Check for Data Snooping
White, H. (2000) · Econometrica · doi:10.1111/1468-0262.00152 · Cited by 1,851 · cited 1×
“In equity markets, Brock et al. (1992) show that technical trading provides significant predictability over 90 years for theDow Jones Industrial Average, while Sullivan et al. (1999) and White (2000) show that the findings of Brock et al. (1992) are not due to data-snooping.”
BackgroundDoes Academic Research Destroy Stock Return Predictability?
MCLEAN, R. D., & PONTIFF, J. (2016) · The Journal of Finance · doi:10.1111/jofi.12365 · Cited by 1,566
Bitcoin, gold and the dollar – A GARCH volatility analysis
Dyhrberg, A. H. (2016) · Finance Research Letters · doi:10.1016/j.frl.2015.10.008 · Cited by 1,544 · cited 1×
“…Bitcoin markets (Urquhart 2016; Nadarajah and Chu 2017; Bariviera 2017; Tiwari et al. 2018), the hedging properties of Bitcoin (Brière et al. 2015; Dyhrberg 2016a,b; Bouri et al. 2017; Urquhart and Zhang 2019), the price discovery within Bitcoin exchanges (Brandvold et al. 2015; Brauneis and…”
Research works printed but not linked: 3
- Chordia, T., Goyal, A., & Saretto, A. (2018). $$p$$-hacking. SSRN Available at: https://ssrn.com/abstract=3017677 (pp. 32–36).
- Young, T. W. (1991). Calmar ratio: A smoother tool. Futures, 20(1), 40.
- Young, T. W. (1991). Calmar ratio: A smoother tool. Futures, 20(1), 40.
Cited by
An index of cryptocurrency environmental attention (ICEA)
Wang, Y., Lucey, B., Vigne, S. A., & Yarovaya, L. (2022) · China Finance Review International · doi:10.1108/cfri-09-2021-0191 · Cited by 181
Herding and feedback trading in cryptocurrency markets
KING, T. L., & Koutmos, D. (2021) · Annals of Operations Research · doi:10.1007/s10479-020-03874-4 · Cited by 109
“…prices) and, since these websites are viewed by many and are publicly available, may contribute to amplify herding behaviors at any given time.5 Hudson and Urquhart (2019) illustrate how technical trading strategies, many of which derive from equity markets and which use past prices to try and…”
BackgroundFinancial modelling, risk management of energy instruments and the role of cryptocurrencies
Huynh, T. L. D., Shahbaz, M. Q., Nasir, M. A., & Ullah, S. (2020) · Annals of Operations Research · doi:10.1007/s10479-020-03680-y · Cited by 102
“1 3 technical trading and returns (Hudson and Urquhart 2019).”
Cryptocurrencies in Modern Finance: A Literature Review
Rejeb, A., Rejeb, K., & Keogh, J. G. (2021) · ETIKONOMI · doi:10.15408/etk.v20i1.16911 · Cited by 121
“In simple terms, cryptocurrencies are a new type of currency (Duque, 2020; Hudson & Urquhart, 2019) that is digital and produced from cryptographic algorithms, exchanged across the Internet using protocols such as peer-to-peer networking (Nakamoto, 2008).”
BackgroundForecasting the volatility of Bitcoin: The importance of jumps and structural breaks
Shen, D., Urquhart, A., & Wang, P. (2019) · European Financial Management · doi:10.1111/eufm.12254 · Cited by 97
Self-citation
Metadata
- Authors
- Hudson, R., & Urquhart, A.
- Affiliations
- University of Hull (GB)
- ICMA Centre (GB)
- Corresponding author
- Urquhart, Andrew
- Venue
- Annals of Operations Research
- Published
- 2019-08-30
- Volume
- 297
- Issue
- 1-2
- Pages
- 191-220
- ISSN
- 0254-5330 (ISSN-L)
- 1572-9338
- OpenAlex
- W2970972678
- Cited by
- 90
- References
- 74
- Citations by year
- 2026: 7 · 2025: 12 · 2024: 9 · 2023: 18 · 2022: 16 · 2021: 20 · 2020: 6 · 2019: 2
- FWCI
- 13.33
- Type
- journal article
- Language
- en
- Open access
- hybrid
- doi.org
- Licence
- cc-by
- creativecommons.org/licenses/by/4.0 (tdm)
- creativecommons.org/licenses/by/4.0 (vor)
- Locations
- Annals of Operations Research (publishedVersion, cc-by)
- CentAUR (University of Reading) (submittedVersion, cc-by)
- Repository@Hull (Worktribe) (University of Hull) (submittedVersion, cc-by)
- RePEc: Research Papers in Economics (submittedVersion)
- Funders
- University of Reading
- Topics
- Social Sciences › Economics, Econometrics and Finance › Finance › Financial Markets and Investment Strategies
- Social Sciences › Decision Sciences › Management Science and Operations Research › Stock Market Forecasting Methods
- Physical Sciences › Computer Science › Information Systems › Blockchain Technology Applications and Security
- Keywords
- technical trading rules, cryptocurrency, Bitcoin, trading rule profitability, predictability, transaction costs, data snooping, multiple comparisons, risk-adjusted returns, out-of-sample predictability
About these checks
Registry, retraction, Cites and statistics results are computed, not judged, with one exception: a printed reference that no index lists is read once by a model before it counts as a citation error. Claims are extracted by a model and kept only when their quote appears verbatim in the text; each cited source is then checked, with a model’s help, for whether it says what the claim relies on. Those verdicts can be wrong — read the claim’s quote and the cited source before relying on one.
The claim verdicts this report counts are experimental: their accuracy is not yet measured.
A language model drew the claims from the paper on 2026-10-10, under version 3 of the claim definition (model deepseek-v4.1-flash, prompt extract-v3).
A second model labelled each claim on 2026-10-10 (model jev-1.13-20260917, definition revision gold-guideline-v0.2).
Cited sources are checked with a language model’s help (gpt-6-sol).
Statistics and arithmetic are recomputed, not judged.
Confidence bands are shown only for fields calibrated on our annotated test set. None is calibrated yet, so no band is shown.
What counts as a claim ›How we measure confidence ›How we check this ›
Are you an author, or do you see a problem with this page? Request a review
How to cite
Cite CoChat for the checks on this page, and the paper for its own findings.
- This page
- CoChat. (2026). Citation check: Technical trading and cryptocurrencies. https://app.cochat.ai/papers/10.1007/s10479-019-03357-1
- The paper
- Hudson, R., & Urquhart, A. (2021). Technical trading and cryptocurrencies. Annals of Operations Research. https://doi.org/10.1007/s10479-019-03357-1
Data sources
Bibliographic data: Semantic Scholar, OpenAlex, Crossref.
Contains information from the Semantic Scholar Academic Graph Datasets, made available under the ODC Attribution License (ODC-BY 1.0).
Semantic Scholar’s data is described in: Kinney, R., et al. (2023). The Semantic Scholar Open Data Platform. arXiv:2301.10140.
