

The DOI matches its Crossref record; 84 of the 85 references it cites were found in a registry or an index.
Risk Everywhere: Modeling and Managing Volatility
Open accessAbstract
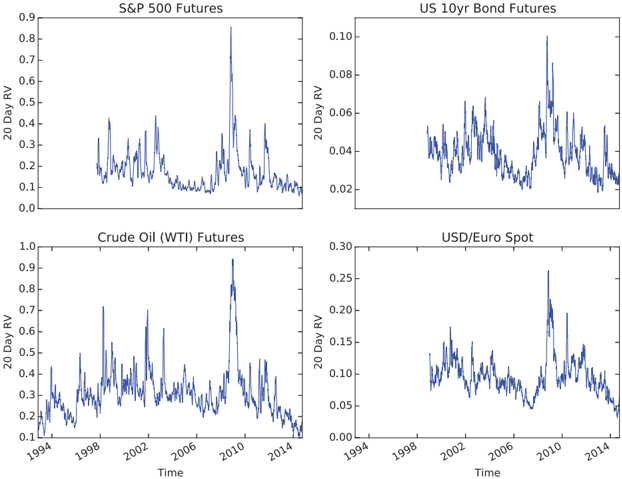
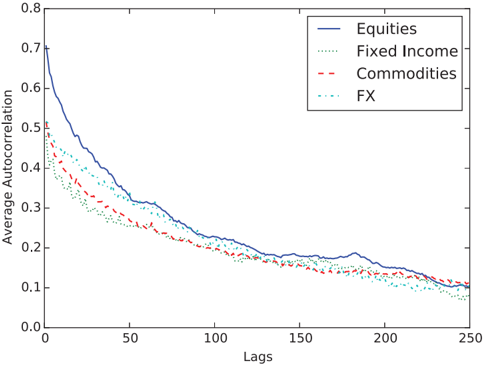
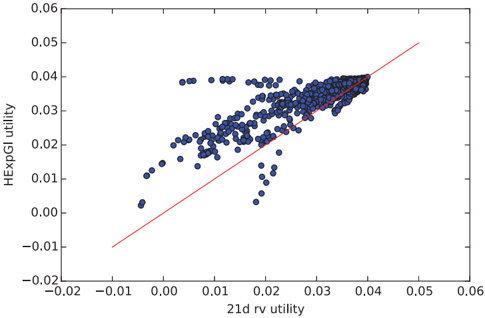
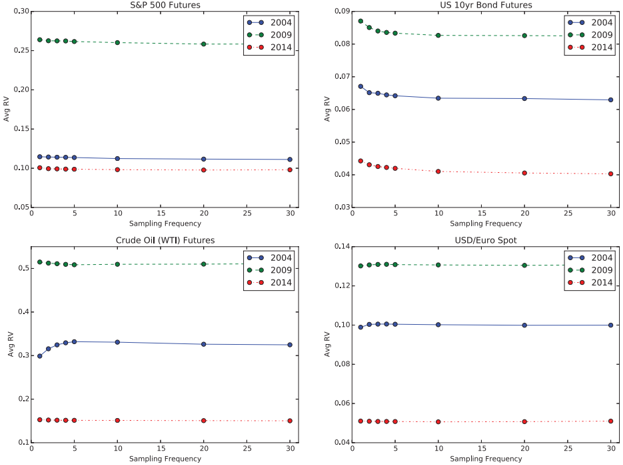
Based on high-frequency data for more than fifty commodities, currencies, equity indices, and fixed-income instruments spanning more than two decades, we document strong similarities in realized volatility patterns within and across asset classes. Exploiting these similarities through panel-based estimation of new realized volatility models results in superior out-of-sample risk forecasts, compared to forecasts from existing models and conventional procedures that do not incorporate the similarities in volatilities. We develop a utility-based framework for evaluating risk models that shows significant economic gains from our new risk model. Lastly, we evaluate the effects of transaction costs and trading speed in implementing different risk models.Received March 7, 2016; editorial decision February 3, 2018 by Editor Andrew Karolyi. Authors have furnished an Internet Appendix, which is available on the Oxford University Press Web site next to the link to the final published paper online.
Overview
The claims and statistics of this paper haven’t been checked yet.
Free: it reads the open-access text and checks the first 5 claims that cite a source we can check. Create a free account to check every claim.
Integrity signals
Registry
Cites
Statistics
Figures





Verification
Claims the paper makes
The claims and statistics of this paper haven’t been checked yet.
Free: it reads the open-access text and checks the first 5 claims that cite a source we can check. Create a free account to check every claim.
Claims other papers make about this one
Each is checked against this paper’s own text: does it say what the citing paper says it does?
The cited source says what the claim attributes to it.
In the citing paper
“Although the transaction cost models of Bollerslev et al. (2018) and Koijen et al. (2018) are quite conservative, we follow an even more cautious approach and deduct 57 bps from each portfolio's monthly excess returns.”
From Empirical asset pricing via machine learning: evidence from the European stock market (2021) · cites this paper as Bollerslev et al. (2018)
Self-check
Percentages, sums and reported differences re-computed from the paper’s own numbers.
The self-check needs the paper’s full text.
Citations
Cites
The Elements of Statistical Learning
Hastie, T., Tibshirani, R., & Friedman, J. (2009) · Springer Series in Statistics · doi:10.1007/978-0-387-84858-7 · Cited by 25,970
Generalized autoregressive conditional heteroskedasticity
Bollerslev, T. (1986) · Journal of Econometrics · doi:10.1016/0304-4076(86)90063-1 · Cited by 22,254
Newey, W. K., & West, K. D. (1987) · Econometrica · doi:10.2307/1913610 · Cited by 16,936
A Simple, Positive Semi-Definite, Heteroskedasticity and AutocorrelationConsistent Covariance Matrix
Newey, W., & West, K. (1986) · National Bureau of Economic Research · doi:10.3386/t0055 · Cited by 12,278
Investor Sentiment and the Cross‐Section of Stock Returns
BAKER, M., & WURGLER, J. (2006) · The Journal of Finance · doi:10.1111/j.1540-6261.2006.00885.x · Cited by 6,049
Diebold, F., & Mariano, R. (1994) · National Bureau of Economic Research · doi:10.3386/t0169 · Cited by 5,185
Diebold, F. X., & Mariano, R. S. (1995) · Journal of Business & Economic Statistics · doi:10.1080/07350015.1995.10524599 · Cited by 5,130
Expected stock returns and volatility
French, K. R., Schwert, G. W., & Stambaugh, R. F. (1987) · Journal of Financial Economics · doi:10.1016/0304-405x(87)90026-2 · Cited by 4,107
Modeling and Forecasting Realized Volatility
Andersen, T. G., Bollerslev, T., Diebold, F. X., & Labys, P. (2003) · Econometrica · doi:10.1111/1468-0262.00418 · Cited by 3,863
Self-citationWhy Does Stock Market Volatility Change Over Time?
SCHWERT, G. W. (1989) · The Journal of Finance · doi:10.1111/j.1540-6261.1989.tb02647.x · Cited by 3,427
Research works printed but not linked: 4
- Andersen,, 2013, Financial risk measuremet for financial risk management.
- Andersen,, 2000, Great realizations., Risk, 13, 105
- Boudoukh,, 2016, Information, trading, and volatilty: Evidence from firm-specific news.
- Engle,, 1996, GARCH for groups., Risk, 9, 36
Cited by
MOREIRA, A., & MUIR, T. (2017) · The Journal of Finance · doi:10.1111/jofi.12513 · Cited by 551
Koijen, R. S. J., Moskowitz, T. J., Pedersen, L. H., & Vrugt, E. B. (2018) · Journal of Financial Economics · doi:10.1016/j.jfineco.2017.11.002 · Cited by 286
Self-citationVolatility of clean energy and natural gas, uncertainty indices, and global economic conditions
Wang, J., Ma, F., Bouri, E., & Zhong, J. (2022) · Energy Economics · doi:10.1016/j.eneco.2022.105904 · Cited by 176
Economic policy uncertainty and the Chinese stock market volatility: Novel evidence
Li, T., Ma, F., Zhang, X., & Zhang, Y. (2020) · Economic Modelling · doi:10.1016/j.econmod.2019.07.002 · Cited by 166
Impact of macroeconomic news, regulation and hacking exchange markets on the volatility of bitcoin
Lyócsa, Š., Molnár, P., Plíhal, T., & Širaňová, M. (2020) · Journal of Economic Dynamics and Control · doi:10.1016/j.jedc.2020.103980 · Cited by 169
Metadata
- Authors
- Bollerslev, T., Hood, B., Huss, J., & Pedersen, L. H.
- Affiliations
- National Bureau of Economic Research (US)
- AQR Capital Management
- Copenhagen Business School (DK)
- Corresponding author
- Pedersen, Lasse Heje
- Venue
- The Review of Financial Studies
- Publisher
- Oxford University Press (OUP)
- Published
- 2018-05-22
- Volume
- 31
- Issue
- 7
- Pages
- 2729-2773
- ISSN
- 0893-9454 (ISSN-L)
- 1465-7368
- OpenAlex
- W3121512573
- Cited by
- 359
- References
- 85
- Citations by year
- 2026: 43 · 2025: 52 · 2024: 52 · 2023: 45 · 2022: 58 · 2021: 33 · 2020: 33 · 2019: 27 · 2018: 12
- FWCI
- 34.69
- Type
- journal article
- Language
- en
- Open access
- hybrid
- doi.org
- Licence
- Locations
- Review of Financial Studies (publishedVersion, cc-by-nc-nd)
- CBS Research Portal (Copenhagen Business School) (submittedVersion, cc-by-nc-nd)
- RePEc: Research Papers in Economics (submittedVersion)
- Funders
- Danmarks Grundforskningsfond (DNRF102)
- FP7 Ideas: European Research Council (312417)
- Topics
- Social Sciences › Economics, Econometrics and Finance › Finance › Financial Risk and Volatility Modeling
- Social Sciences › Economics, Econometrics and Finance › Finance › Stochastic processes and financial applications
- Social Sciences › Economics, Econometrics and Finance › Finance › Financial Markets and Investment Strategies
- Keywords
- realized volatility, volatility modeling, volatility forecasting, out-of-sample forecasting, risk management, transaction costs, trading speed, high-frequency data
About these checks
Registry, retraction, Cites and statistics results are computed, not judged, with one exception: a printed reference that no index lists is read once by a model before it counts as a citation error. Claims are extracted by a model and kept only when their quote appears verbatim in the text; each cited source is then checked, with a model’s help, for whether it says what the claim relies on. Those verdicts can be wrong — read the claim’s quote and the cited source before relying on one.
Statistics and arithmetic are recomputed, not judged.
Confidence bands are shown only for fields calibrated on our annotated test set. None is calibrated yet, so no band is shown.
What counts as a claim ›How we measure confidence ›How we check this ›
Are you an author, or do you see a problem with this page? Request a review
How to cite
Cite CoChat for the checks on this page, and the paper for its own findings.
- This page
- CoChat. (2026). Citation check: Risk Everywhere: Modeling and Managing Volatility. https://app.cochat.ai/papers/10.1093/rfs/hhy041
- The paper
- Bollerslev, T., Hood, B., Huss, J., & Pedersen, L. H. (2018). Risk Everywhere: Modeling and Managing Volatility. The Review of Financial Studies. https://doi.org/10.1093/rfs/hhy041
Data sources
Bibliographic data: Semantic Scholar, OpenAlex, Crossref.
Contains information from the Semantic Scholar Academic Graph Datasets, made available under the ODC Attribution License (ODC-BY 1.0).
Semantic Scholar’s data is described in: Kinney, R., et al. (2023). The Semantic Scholar Open Data Platform. arXiv:2301.10140.
